Press Releases
Release of 3rd Quarter 2026 real estate statistics
23 October 2026
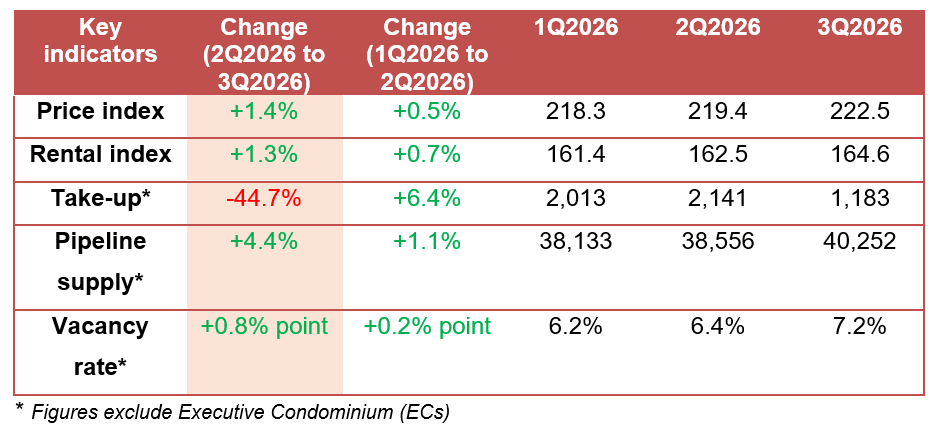
The overall private residential property price index increased by an average of 0.9% per quarter in the first three quarters of 2026, similar to that for the corresponding period in 2025. The increase in the property price index was 1.4% in 3rd Quarter 2026, compared to 0.5% in the preceding quarter.
To cater to housing demand and maintain market stability, the Government has continued to sustain a high level of private housing supply through the Government Land Sales (GLS) Programme. A total of 4,745 private residential units will be launched under the Confirmed List in the second half of 2026, bringing the full-year Confirmed List supply to 9,320 units, more than 50% above the annual average over the past 10 years. With the large GLS supply injection, a significant supply of more than 32,000 private housing units (including Executive Condominium units) could be made available for sale over the next one to two years. This is part of the total supply of 57,200 private residential units expected to be completed over the next few years.
The macroeconomic outlook remains highly uncertain, including for global and domestic interest rates. Households are advised to exercise prudence when purchasing property and taking out mortgage loans.
The Urban Redevelopment Authority (URA) released today the real estate statistics for 3rd Quarter 2026.
Private residential properties
Overview
Prices and rentals
Prices of private residential properties increased by 1.4% in 3rd Quarter 2026, compared with the 0.5% increase in the previous quarter.
Property Price Index of private residential properties
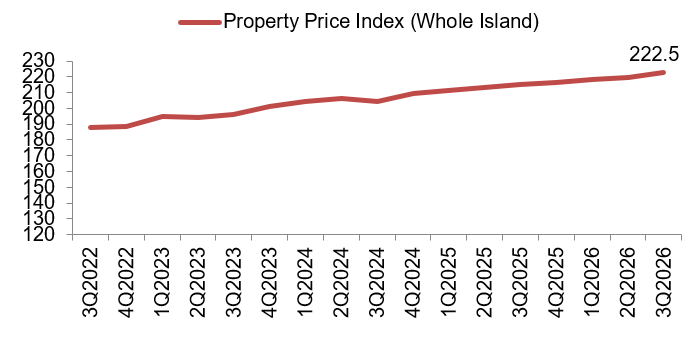
Prices of landed properties increased by 2.9% in 3rd Quarter 2026, compared with the 2.5% increase in the previous quarter. Prices of non-landed properties increased by 1.0% in 3rd Quarter 2026, compared with the 0.1% decrease in the previous quarter.
Prices of non-landed properties in Core Central Region (CCR) increased by 0.3% in 3rd Quarter 2026, compared with the 1.8% increase in the previous quarter. Prices of non-landed properties in Rest of Central Region (RCR) remained unchanged in 3rd Quarter 2026, compared with the 1.2% decrease in the previous quarter. Prices of non-landed properties in Outside Central Region (OCR) increased by 2.3% in 3rd Quarter 2026, compared with the 0.1% decrease in the previous quarter (see Annex A-1 (opens in new tab)).
Rentals of private residential properties increased by 1.3% in 3rd Quarter 2026, compared with the 0.7% increase in the previous quarter.
Rental Index of private residential properties
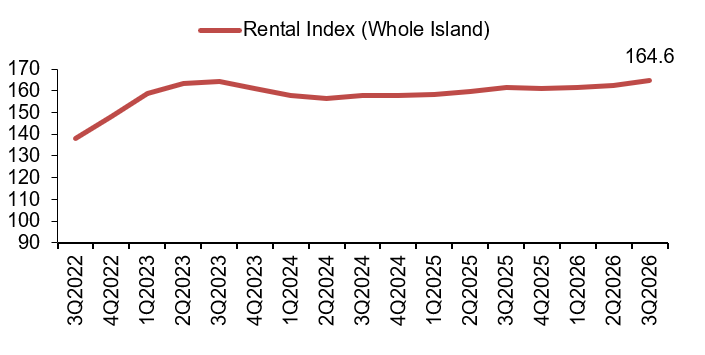
Rentals of non-landed properties increased by 1.2% in 3rd Quarter 2026, compared with the 0.4% increase in the previous quarter. Rentals of landed properties increased by 2.1% in 3rd Quarter 2026, compared with the 2.7% increase in the previous quarter.
Rentals of non-landed properties in CCR decreased by 0.3% in 3rd Quarter 2026, compared with the 1.2% increase in the previous quarter. Rentals of non-landed properties in RCR increased by 1.5% in 3rd Quarter 2026 after remaining unchanged in the previous quarter. Rentals of non-landed properties in OCR increased by 3.1% in 3rd Quarter 2026, compared with the 0.3% decrease in the previous quarter (See Annex A-2 (opens in new tab)).
Launches and take-up
Developers launched 1,140 uncompleted private residential units (excluding ECs) for sale in 3rd Quarter 2026, compared with the 1,783 units in the previous quarter (see Annex C (opens in new tab)).
Developers sold 1,183 private residential units (excluding ECs) in 3rd Quarter 2026, compared with the 2,141 units sold in the previous quarter (see Annex D (opens in new tab)).
Number of private housing units launched and sold by developers (excluding ECs)
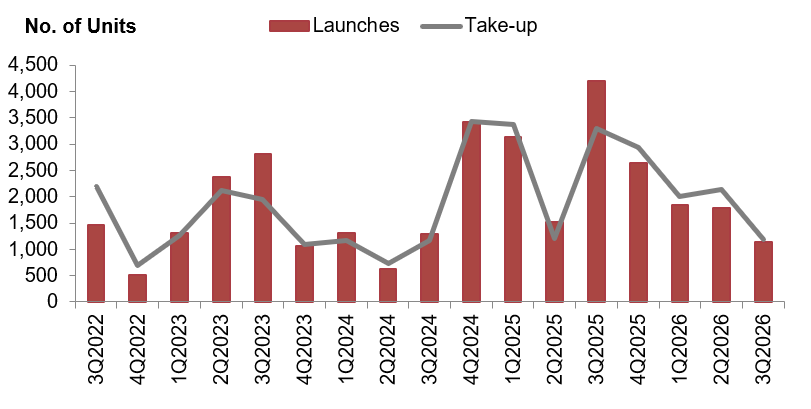
Developers did not launch any EC units for sale in 3rd Quarter 2026 and sold 68 units in the quarter (see Annex F (opens in new tab)). In comparison, developers did not launch any EC units for sale and sold 175 EC units in the previous quarter.
Resales and sub-sales
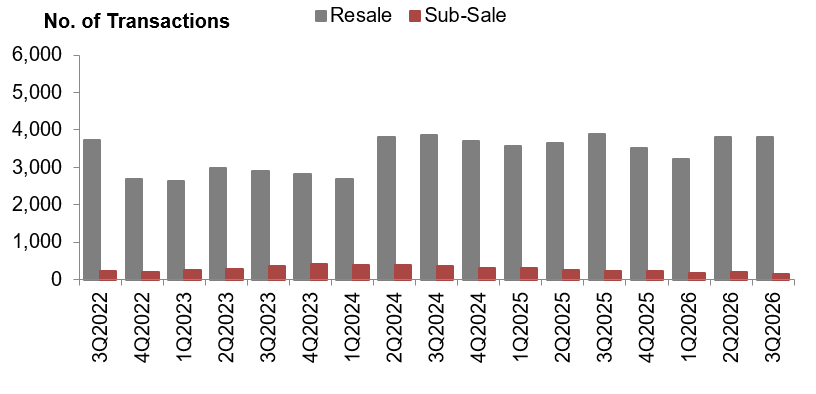
There were 3,801 resale transactions in 3rd Quarter 2026, compared with the 3,813 units transacted in the previous quarter. Resale transactions accounted for 73.9% of all sale transactions in 3rd Quarter 2026, compared with 62.0% in the previous quarter (see Annex D (opens in new tab)).
There were 162 sub-sale transactions in 3rd Quarter 2026, compared with the 194 sub-sale transactions in the previous quarter. Sub-sales accounted for 3.1% of all sale transactions in 3rd Quarter 2026, compared with 3.2% in the previous quarter (See Annex D (opens in new tab)).
Number of resale and sub-sale transactions for private residential units (excluding ECs)
Supply completions
A total of 3,559 private residential units (including ECs) were completed in 3rd Quarter 2026, an increase from the 1,212 units completed in the previous quarter. This was the highest quarterly completion recorded since 3rd Quarter 2024 (See Annex E-4 (opens in new tab)).
Supply in the pipeline
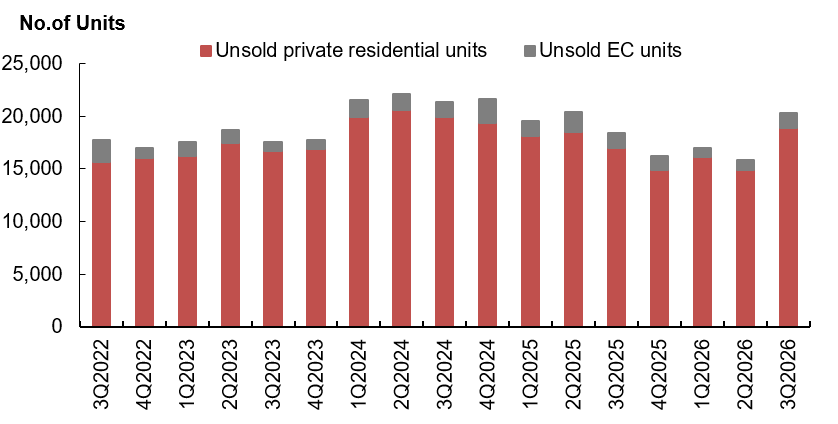
As at the end of 3rd Quarter 2026, there were 44,738 units (including ECs) with planning approval, of which 20,300 units remained unsold (see Annexes B (opens in new tab) & E-1 (opens in new tab)). Adding 12,508 unsold units (including ECs) that have not been granted planning approval yet, approximately 32,800 units could be made available for sale in the next one to two years. These include the supply of about 4,745 units (including 735 EC units) on the Confirmed List of the GLS Programme in 2H2026 (see Annex E-3 (opens in new tab)).
Total number of unsold private residential units with planning approval in the pipeline
Based on the expected completion dates reported by developers, about 57,200 private housing units are expected to be completed in the coming years. These comprise about 22,300 units (including ECs) expected to be completed by 2028, and about 34,900 units expected to be completed from 2029 onwards (see Annex E-3 (opens in new tab)).
Pipeline supply of private residential units and ECs by expected year of completion
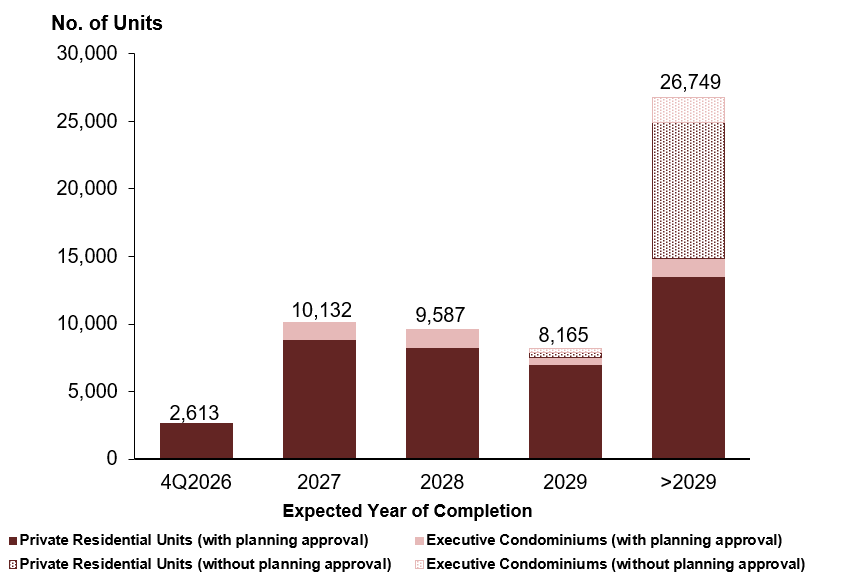
Note: 5,170 private residential units and 872 executive condominiums were completed (i.e. obtained TOP) in 1Q-3Q2026.
Stock and vacancy
The stock of completed private residential units (excluding ECs) increased by 3,491 units in 3rd Quarter 2026, compared with the increase of 416 units in the previous quarter. The stock of occupied private residential units (excluding ECs) decreased by 305 units in 3rd Quarter 2026, compared with the decrease of 387 units in the previous quarter. As a result, the vacancy rate of completed private residential units (excluding ECs) increased to 7.2% as at the end of 3rd Quarter 2026, from 6.4% in the previous quarter (see Annex E-1 (opens in new tab)).
Stock and vacancy of private residential units (excluding ECs)
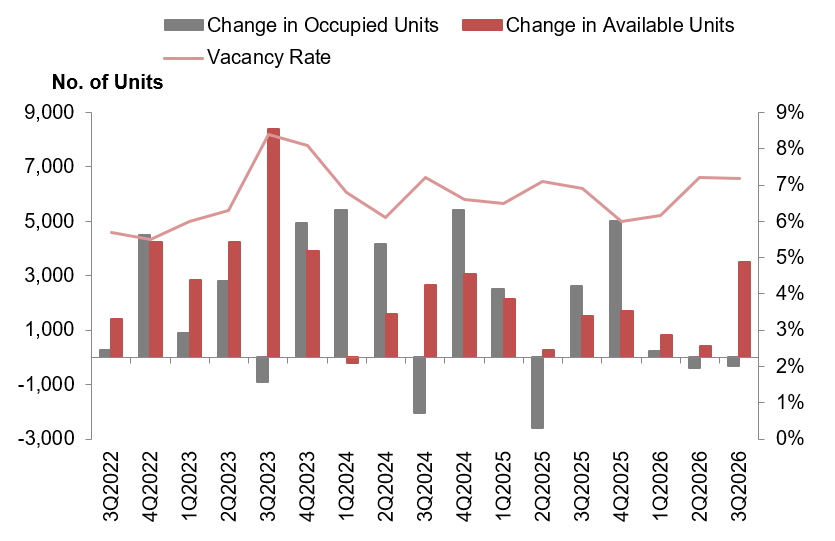
Vacancy rates of completed private residential properties as at the end of 3rd Quarter 2026 in CCR, RCR and OCR were 8.4%, 7.4% and 6.5% respectively, compared with the 8.3%, 6.1% and 5.6% in the previous quarter.
Office space
Overview
Prices and rentals
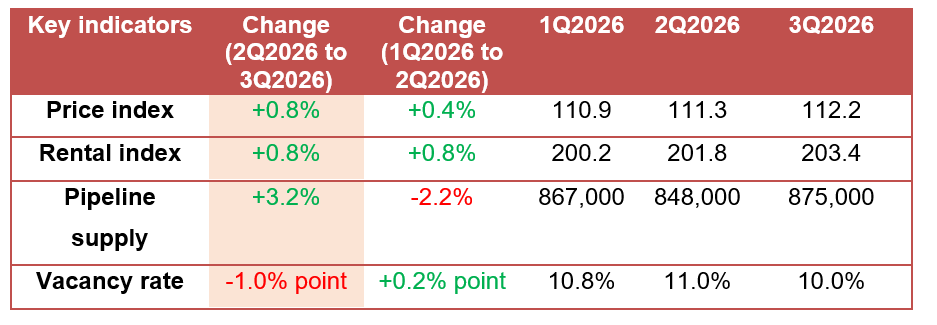
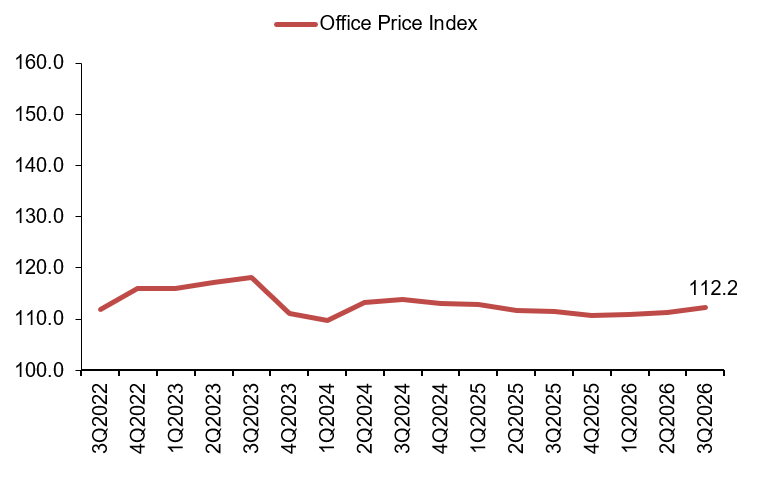
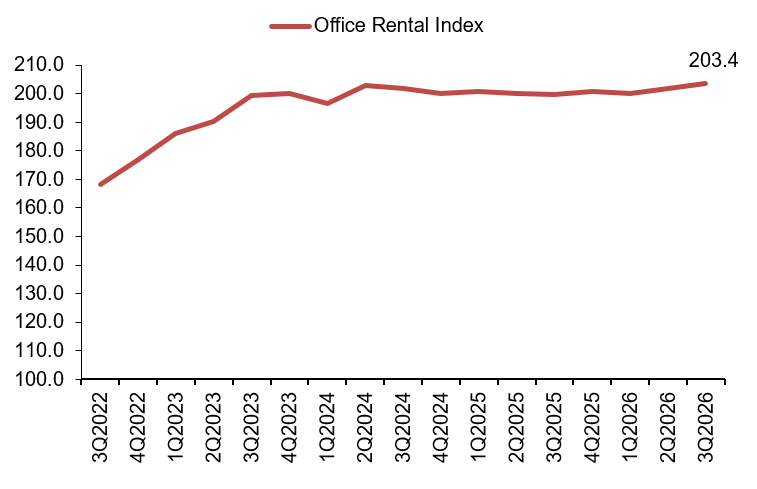
Prices of office space increased by 0.8% in 3rd Quarter 2026, compared with the 0.4% increase in the previous quarter (See Annex A-1 (opens in new tab)). Rentals of office space increased by 0.8% in 3rd Quarter 2026, same as the 0.8% increase in the previous quarter (See Annex A-2 (opens in new tab)).
Property Price Index of office space in Central Region
Rental Index of office space in Central Region
Note: Office rental statistics, including breakdown by location, floor area and building class, as well as street-level rental data, are updated quarterly and can be accessed at Commercial Office Rental Analysis (opens in new tab) and Rental Statistics for Office and Retail Space by Street (opens in new tab)
Supply in the pipeline
As at the end of 3rd Quarter 2026, there was a total supply of about 875,000 sq m GFA of office space in the pipeline, compared with the 848,000 sq m GFA of office space in the pipeline in the previous quarter (see Annexes E-1 (opens in new tab)& E-2 (opens in new tab)).
Pipeline supply of office space
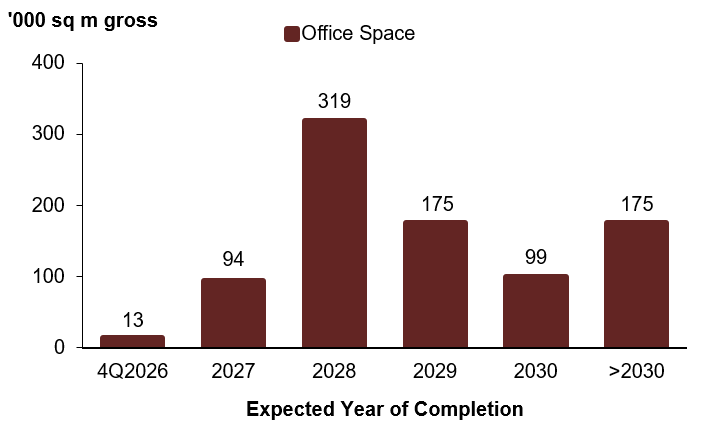
Note: 47,936 sq m of office space was completed (i.e. granted TOP) in 1Q-3Q2026.
Stock and vacancy
The amount of occupied office space increased by 17,000 sq m (nett) in 3rd Quarter 2026, compared with the increase of 8,000 sq m (nett) in the previous quarter. The stock of office space decreased by 72,000 sq m (nett) in 3rd Quarter 2026, compared with the increase of 19,000 sq m (nett) in the previous quarter. As a result, the island-wide vacancy rate of office space decreased to 10.0% as at the end of 3rd Quarter 2026, from 11.0% as at the end of the previous quarter (see Annex E-1 (opens in new tab)).
Stock and vacancy of office space
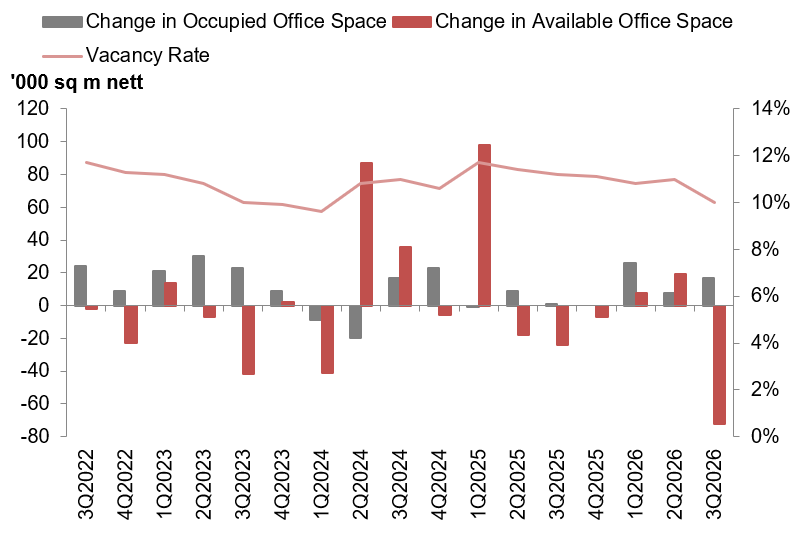
Note: Vacancy rate statistics for office spaces, including breakdown by building class, are updated quarterly and can be accessed at Commercial Property Time Series Statistics (opens in new tab)
Retail space
Overview
Prices and rentals
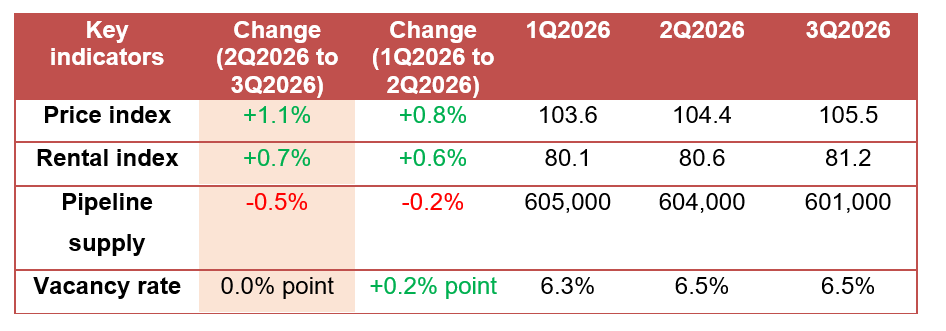
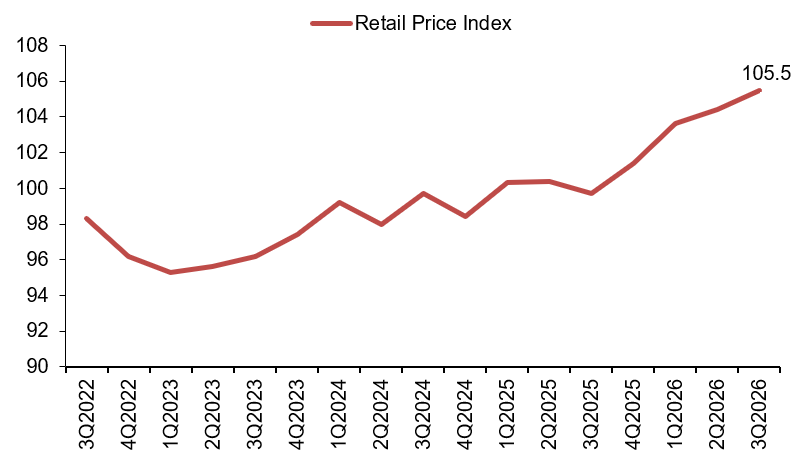
Prices of retail space increased by 1.1% in 3rd Quarter 2026, compared with the 0.8% increase in the previous quarter (See Annex A-1 (opens in new tab)). Rentals of retail space increased by 0.7% in 3rd Quarter 2026, compared with the 0.6% increase in the previous quarter (See Annex A-2 (opens in new tab)).
Property Price Index of retail space in Central Region
Rental Index of retail space in Central Region
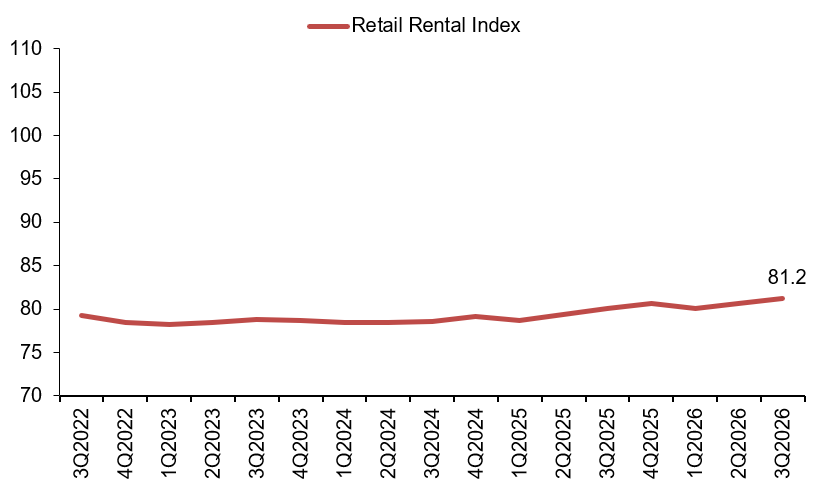
Note: Retail rental statistics, including breakdown by postal district, floor level and floor area, as well as street-level rental data, are updated quarterly and can be accessed at Commercial Retail Rental Analysis (opens in new tab) and Rental Statistics for Office and Retail Space by Street (opens in new tab)
Supply in the pipeline
As at the end of 3rd Quarter 2026, there was a total supply of about 601,000 sq m GFA of retail space in the pipeline, compared with the 604,000 sq m GFA of retail space in the pipeline in the previous quarter (see Annexes E-1 (opens in new tab)& E-2 (opens in new tab)).
Pipeline supply of retail space
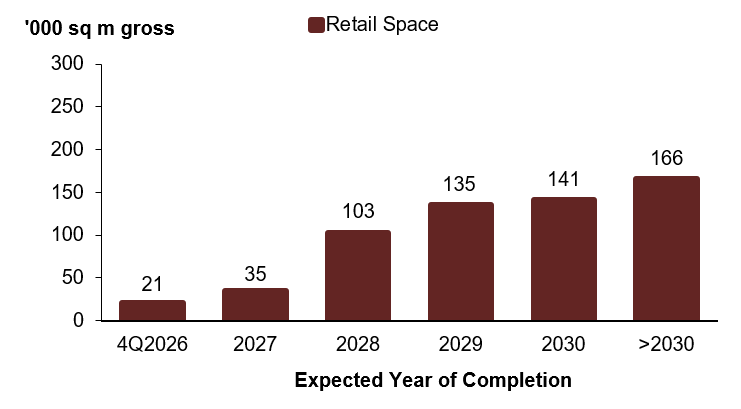
Note: 19,055 sq m of retail space was completed (i.e. granted TOP) in 1Q-3Q2026.
Stock and vacancy
The amount of occupied retail space decreased by 21,000 sq m (nett) in 3rd Quarter 2026, compared with the decrease of 37,000 sq m (nett) in the previous quarter. The stock of retail space decreased by 20,000 sq m (nett) in 3rd Quarter 2026, compared with the decrease of 28,000 sq m (nett) in the previous quarter. As a result, the island-wide vacancy rate of retail space remained at 6.5% as at the end of 3rd Quarter 2026, the same as at the end of the previous quarter (see Annex E-1 (opens in new tab)).
Stock and vacancy of retail space
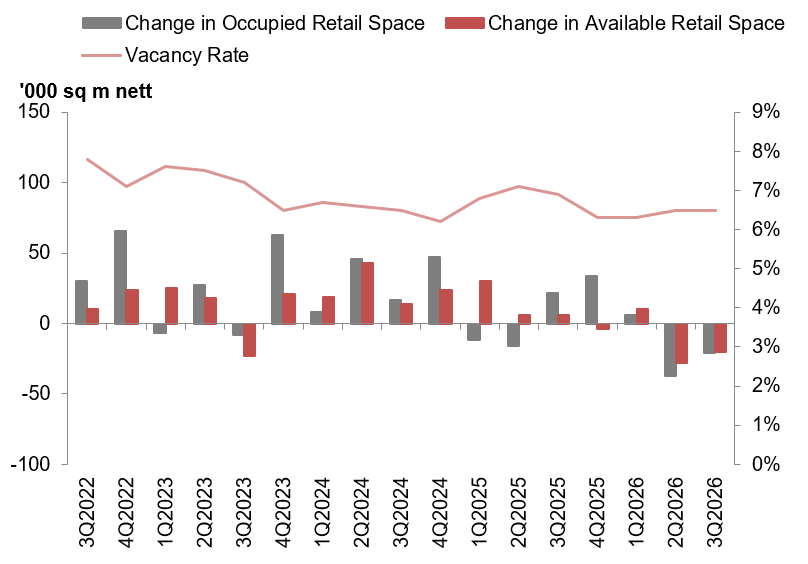
Note: Vacancy rate statistics for retail spaces, including the breakdown by location, are updated quarterly and can be accessed at Commercial Property Time Series Statistics (opens in new tab)
URA’s real estate information service
Real estate information, such as time series statistics, are available on the URA website. Visit Private Residential Time Series Statistics (opens in new tab) for time series statistics on private residential properties and Commercial Property Time Series Statistics (opens in new tab) for time series statistics on commercial properties.
Detailed information on the price and rental indices, supply in the pipeline, stock and vacancy rates of the various property sectors can be found in the Real Estate Information System (REALIS) (opens in new tab). A subscription is required to access REALIS.
The figures in this release are accurate as of 23 October 2026. Please visit the URA website or REALIS for the most updated figures.
Summary of key information for 3rd Quarter 2026
Annex | Title |
|---|---|
Comparison of property price index for 2nd Quarter 2026 and 3rd Quarter 2026 | |
Comparison of rental index for 2nd Quarter 2026 and 3rd Quarter 2026 | |
Number of unsold private residential units from projects with planning approvals | |
Number of uncompleted private residential units launched in the quarter by market segment | |
Number of new sale, sub-sale and resale transactions for private residential units by market segment | |
Stock & vacancy and supply in the pipeline as at end of 3rd Quarter 2026 | |
Supply in the pipeline and expected year of completion as at end of 3rd Quarter 2026 | |
Pipeline supply of private residential units and executive condominiums by expected year of completion as at end of 3rd Quarter 2026 | |
Number of private residential units and executive condominiums completed in the quarter | |
Number of executive condominium units launched and sold in the quarter |